Unveiling the Hidden Answers: Decoding Chapter 2 Economic Systems and Decision Making

Understanding economic systems and how decisions are made is crucial to understanding the functioning of any society. In this chapter, we will explore the various economic systems that exist and the factors that influence decision-making processes. We will also examine the advantages and disadvantages of different economic systems.
An economic system is a set of rules and structures that govern the production and distribution of goods and services within a society. It determines how resources are allocated and how decisions about production and consumption are made. There are four main types of economic systems: traditional, command, market, and mixed.
In a traditional economic system, economic decisions and production processes are based on customs, traditions, and beliefs. This system is often found in rural and less developed regions, where people rely on agriculture and hunting for their livelihoods. In this system, decisions are made based on what has been done in the past and are often passed down from generation to generation. While this system provides stability and predictability, it can also hinder innovation and economic growth.
In a command economic system, the government or a central authority makes all economic decisions and controls the means of production. This system is often associated with communism and socialism. The government determines what goods and services are produced, how they are produced, and how they are distributed. While this system can promote equality and ensure that basic needs are met, it can also lead to inefficiency and lack of incentive for innovation.
What Are Economic Systems?

An economic system refers to the way a society organizes the production, distribution, and consumption of goods and services. It is the framework that guides how resources are allocated and how economic decisions are made. Economic systems can vary across different countries and cultures, reflecting different values, priorities, and levels of government intervention.
There are different types of economic systems, including market economies, command economies, and mixed economies. In a market economy, also known as capitalism, resources are primarily owned and controlled by individuals and businesses. Prices and wages are determined by supply and demand, and decisions about what to produce, how to produce, and for whom to produce are made by individuals and businesses in pursuit of profit.
In contrast, a command economy, also known as socialism or communism, is characterized by government ownership and control of resources and the means of production. Prices and wages are often set by the government, and decisions about what to produce, how to produce, and for whom to produce are made by the government or central planning authority.
A mixed economy, as the name suggests, combines elements of both market and command economies. It allows for private ownership and control of resources and businesses, but also involves government intervention and regulation to ensure equitable distribution of wealth and address market failures.
Each economic system has its strengths and weaknesses, and no system is perfect. Market economies are often praised for their efficiency and ability to incentivize innovation and entrepreneurship, but critics argue that they can lead to inequality and lack of social safety nets. Command economies, on the other hand, are often praised for their focus on equality and social welfare, but critics argue that they can stifle individual initiative and innovation.
Ultimately, the choice of an economic system depends on the values, goals, and priorities of a society. It is a complex decision that involves trade-offs and compromises, and requires continual evaluation and adjustment to meet the changing needs and circumstances of the society.
Understanding Economic Systems
Economic systems are the ways in which societies organize and allocate their resources to produce goods and services. They determine how resources are owned, used, and distributed within a society. Understanding economic systems is crucial for analyzing how different societies function and make decisions about production, consumption, and distribution.
In a market economy, resources are owned and controlled by individuals and businesses. Decisions about production and consumption are made by individuals and are guided by the forces of supply and demand. Competition among producers and consumers dictates prices and drives economic activity. Market economies are characterized by private property rights, voluntary exchange, and limited government intervention. The United States is an example of a market economy.
In contrast, command economies are centrally planned and controlled by the government. The state owns and controls all resources and makes decisions about production, consumption, and distribution. Prices are set by the government, and individuals have limited control over economic decisions. Command economies are characterized by government ownership of resources, state control over economic planning, and limited individual freedom. North Korea is an example of a command economy.
Traditional economies
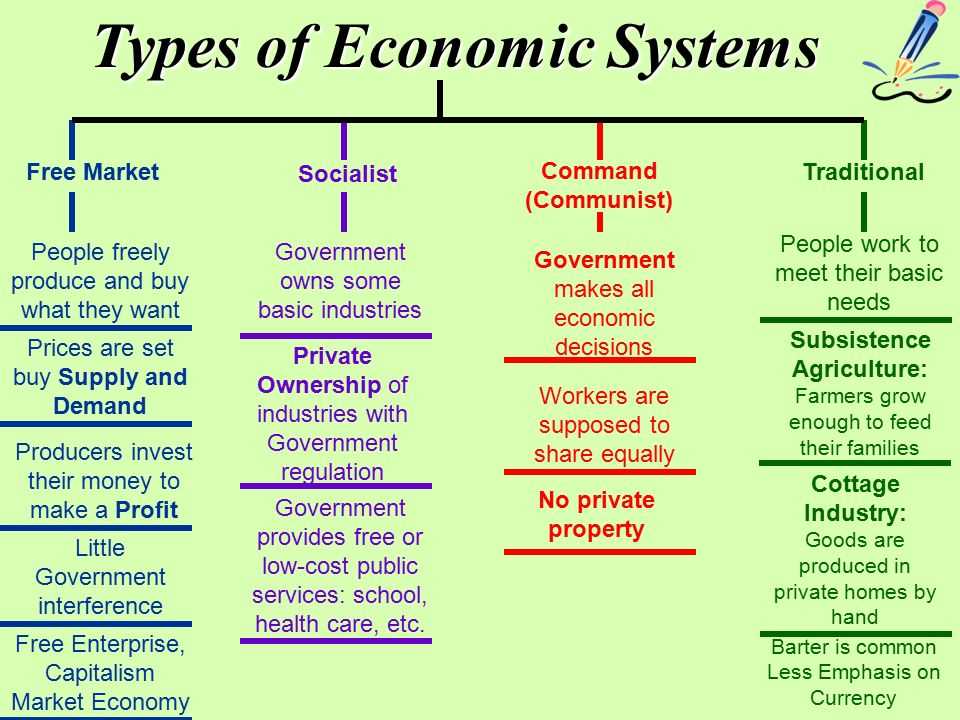
Traditional economies are the oldest and simplest economic systems. They rely on customs, traditions, and cultural norms to make decisions about resource allocation. Traditional economies are typically found in rural and tribal societies where subsistence farming and hunting are the primary means of survival. In these economies, resources are owned and used collectively by the community, and economic decisions are based on traditional practices and beliefs. Traditional economies tend to have little economic growth or innovation and are resistant to change. Indigenous communities in remote parts of the world often have traditional economies.
Mixed economies
In many modern societies, economic systems are a mix of market and command elements. These mixed economies combine private enterprise with government intervention to achieve economic goals. Governments in mixed economies provide public goods and services, regulate markets, and redistribute wealth through taxes and social welfare programs. Mixed economies aim to balance individual freedom and market efficiency with social equity and stability. Countries like Sweden and Canada have mixed economies.
Main Types of Economic Systems
An economic system refers to the way a society organizes the production, allocation, and distribution of goods and services. There are three main types of economic systems: market economy, command economy, and mixed economy.
Market Economy
In a market economy, also known as a free market or capitalism, the means of production are privately owned. The role of the government is limited, and decisions on what to produce, how to produce, and for whom to produce are largely determined by market forces of supply and demand. Individuals and businesses are motivated by profit and are free to make economic decisions without government interference. Prices are determined by the interaction of buyers and sellers in the marketplace. Examples of market economies include the United States, Canada, and Singapore.
Command Economy
In a command economy, also known as socialism or communism, the means of production are owned and controlled by the government. The government makes all economic decisions, including what to produce, how to produce, and for whom to produce. The goal of a command economy is to achieve equality and prosperity for all members of society. Prices are set by the government, and individual freedoms and private property rights may be limited. Examples of command economies include North Korea and Cuba.
Mixed Economy
A mixed economy combines elements of both market and command economies. In a mixed economy, the government and the private sector coexist and share responsibility for economic decision making. Some industries may be privately owned and operated, while others may be owned and regulated by the government. The government typically intervenes in the economy to ensure fairness, protect consumers, and provide public goods and services. Examples of mixed economies include the United Kingdom, Germany, and Australia.
Overall, the economic system of a country plays a significant role in determining the level of economic growth, efficiency, and equity within that society. Each type of economic system has its advantages and disadvantages, and different countries have adopted different systems based on their unique circumstances and priorities.
Characteristics of a Market Economy
A market economy is a type of economic system where decisions regarding production, investment, and distribution are based on the forces of supply and demand in the marketplace. This system is characterized by several key features that distinguish it from other types of economic systems.
Private Ownership: In a market economy, most of the resources and means of production are privately owned and controlled by individuals or businesses. This ownership allows individuals to make independent decisions about how to allocate their resources and invest in production.
Profit Motive: One of the primary driving forces in a market economy is the profit motive. Individuals and businesses seek to maximize their profits by producing and selling goods and services that are in demand. This incentive encourages efficiency and innovation, as producers strive to offer better products at competitive prices in order to attract customers.
Competition: A market economy thrives on competition. In this system, multiple producers and sellers compete with one another for customers. This competition fosters efficiency and productivity, as businesses strive to offer better quality products and services while keeping costs low. It also allows consumers to have a wide variety of choices and to benefit from lower prices.
Price System: In a market economy, prices are determined by the forces of supply and demand. The interaction of buyers and sellers in the marketplace sets the price for goods and services. Prices act as signals, conveying information about scarcity and consumer preferences. They also play a crucial role in allocating resources and determining how goods and services are produced and distributed.
Limited Government Intervention: In a market economy, there is minimal government intervention in economic activities. The government’s role is primarily focused on creating and enforcing laws that protect property rights, prevent fraud, and ensure fair competition. By allowing individuals and businesses to make their own economic decisions, a market economy promotes individual freedom and entrepreneurship.
Overall, a market economy relies on the principles of private ownership, profit motive, competition, price system, and limited government intervention to drive economic growth and allocate resources efficiently. It has been widely adopted by many countries around the world as a means to promote economic development and improve living standards.
Characteristics of a Command Economy
In a command economy, also known as a planned economy, the government has strict control over the allocation of resources and the production of goods and services. This type of economic system is characterized by centralized decision-making, where government authorities determine what is produced, how it is produced, and who will receive the goods and services.
One key characteristic of a command economy is the absence of private ownership and market competition. In this system, all resources are collectively owned by the government or the state, and there is no individual ownership. The government determines the prices of goods and services, sets production targets, and controls the distribution of resources.
Centralized Planning and Control
- In a command economy, economic planning is performed by a central authority, usually the government. This central authority makes all major economic decisions, such as what to produce, how much to produce, and how resources should be allocated.
- This centralized planning allows the government to prioritize the production of certain goods and services that are considered essential for the society. It also allows the government to regulate the allocation of resources to achieve specific objectives, such as economic growth or social welfare.
State Ownership and Control
- In a command economy, the government or the state owns and controls the means of production, including factories, land, and other productive assets. This means that all economic activities are conducted under the direct control of the government.
- The state determines the prices of goods and services, which are often set below market prices to ensure affordability for the population. It also regulates the distribution of resources, ensuring that goods and services are allocated based on the government’s priorities, rather than market forces.
| Advantages | Disadvantages |
|---|---|
| The government can prioritize the production of essential goods and services. | Lack of incentives for innovation and entrepreneurship. |
| Reduced income inequality. | Centralized decision-making can lead to inefficiency and misallocation of resources. |
| Greater control over the economy to achieve specific objectives, such as economic growth or social welfare. | Lack of consumer choice and limited variety of goods and services. |
Mixed Economic Systems
A mixed economic system is a combination of both a market economy and a command economy. In this type of system, the government and individuals share the responsibility for making economic decisions. The government plays a role in regulating certain industries and providing public goods and services, while individuals and businesses have the freedom to make their own economic choices.
In a mixed economic system, private property is recognized and protected, which provides individuals with the incentive to work hard and be productive. At the same time, the government may intervene in the economy to address market failures and promote overall economic stability. This can include measures such as implementing regulations, providing social welfare programs, and redistributing wealth.
Advantages of a mixed economic system:
- Individuals have the freedom to pursue their own economic interests and make choices based on their own preferences.
- The government can step in to address market failures and ensure that essential goods and services are available to everyone.
- There is a balance between individual freedom and government intervention, potentially leading to a more stable and equitable economy.
Disadvantages of a mixed economic system:
- There can be conflicts between government regulations and individual freedoms.
- The government’s role in the economy can lead to inefficiencies and bureaucracy.
- It can be challenging to find the right balance between government intervention and free market principles.
Overall, a mixed economic system attempts to combine the strengths of both market economies and command economies. It recognizes the importance of individual freedom and market forces, while also acknowledging the need for government intervention to ensure fairness and address societal concerns.