Affordable care act basics exam answers
To master the key concepts of the U.S. health reform, focus on the primary provisions that shape the current system. Ensure that you understand the role of insurance exchanges and the guidelines for eligibility. Knowing the structure of subsidies, penalties for non-compliance, and the protections for pre-existing conditions is essential for scoring well on the assessment.
Focus on the requirement for most Americans to obtain health coverage, and the exceptions to this rule. It is important to grasp the different coverage levels offered through the marketplace and how they impact both individuals and businesses. Familiarize yourself with the penalties tied to non-compliance, and the strategies used to support low-income families through financial assistance.
Key takeaways: Health plans must meet certain minimum standards, and insurance providers can no longer deny coverage based on health status. Recognize how Medicaid expansion plays a role in expanding access to low-income individuals and the importance of preventative care in reducing long-term costs.
To excel in your understanding of the reform’s core components, be sure to study the various policy shifts that influence the affordability of coverage and the responsibilities placed on both insurers and consumers.
Affordable Care Act Basics Exam Answers
To succeed in the assessment on health coverage reforms, focus on these critical points:
1. The individual mandate, requiring most Americans to have health insurance or face a penalty, was initially a key component but was effectively nullified in 2019.
2. Medicaid expansion, providing coverage for low-income adults, was offered to states but was not mandatory. States had the choice to expand this program.
3. The creation of health insurance exchanges (marketplaces) allowed individuals to compare plans and access subsidies based on income.
4. Insurance companies were prohibited from denying coverage based on pre-existing conditions.
5. Children could stay on their parents’ insurance plan until the age of 26.
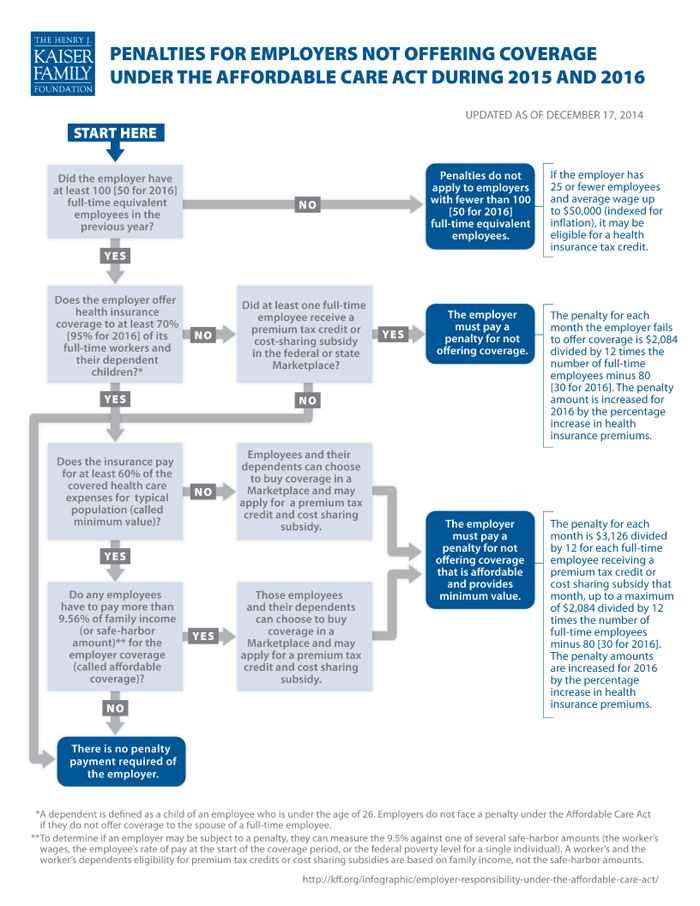
6. The employer mandate required large employers to offer health coverage to full-time workers or pay penalties. Knowing these core details and the specific provisions they affect will guide your success in this topic’s review.
Understanding Key Provisions of the Affordable Care Act
The law introduced critical changes to the healthcare system, focusing on expanding access, reducing costs, and improving quality of services. The following provisions are central to its objectives:
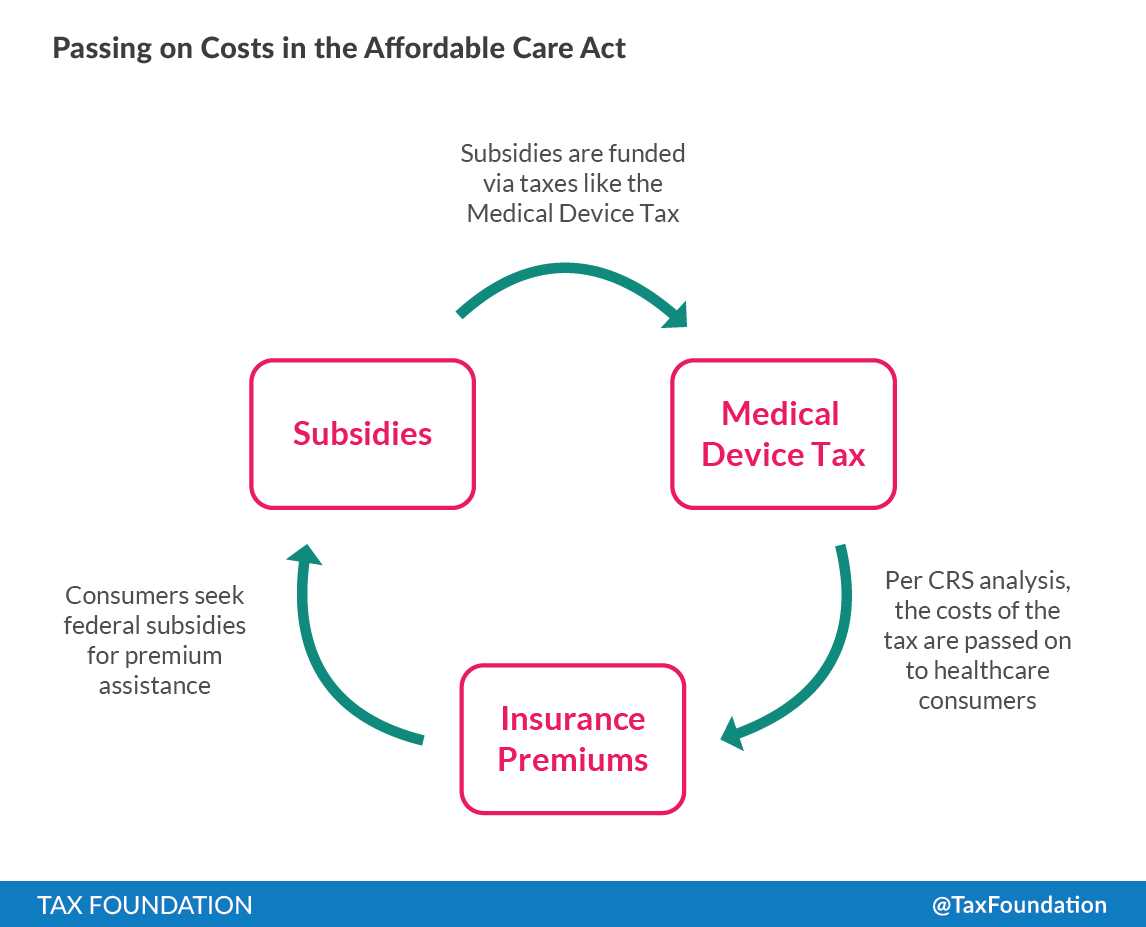
- Health Insurance Marketplaces: State-based platforms, or federal exchanges, allow individuals and small businesses to compare and purchase health insurance plans with subsidies available based on income levels.
- Medicaid Expansion: Expands eligibility for Medicaid, enabling millions more low-income individuals to access health coverage in participating states.
- Individual Mandate: Initially required most Americans to have health insurance or face a penalty. This provision was reduced to zero in 2019 at the federal level, though some states maintain their own mandates.
- Pre-existing Conditions Protection: Prevents insurers from denying coverage or charging higher premiums based on an individual’s health history.
- Essential Health Benefits: Requires insurance plans to cover a set of core services, such as emergency services, maternity care, and prescription drugs.
- Employer Mandate: Employers with 50 or more full-time employees must offer affordable health coverage to their workers or face penalties.
- Subsidies for Low-Income Households: Individuals and families with incomes between 100% and 400% of the federal poverty level are eligible for financial assistance to purchase insurance through the marketplace.
- Young Adult Coverage: Allows individuals to remain on their parent’s insurance plan until age 26, expanding access for younger populations.
- Preventive Services Coverage: Mandates that most insurance plans cover preventive services like vaccinations, screenings, and wellness visits at no additional cost to the insured.
Understanding these key provisions helps in making informed decisions about healthcare coverage, whether through the marketplace, employer-provided plans, or government programs.
How the ACA Impacts Health Insurance Coverage Options
The legislation has significantly reshaped the availability of health insurance by establishing health marketplaces, expanding Medicaid in many states, and setting minimum coverage standards for insurers. Individuals now have access to a broader range of coverage options, often with subsidies based on income levels. States that adopted Medicaid expansion have seen increased access to coverage for low-income populations, filling a gap in insurance options for many adults without children.
Health insurance plans offered through the marketplace are required to cover a set of essential health benefits, including hospital and emergency services, maternity and newborn care, and mental health services. These minimum standards mean that consumers are assured a base level of coverage, without worrying about gaps in their care.
For employers, the requirement to provide health insurance for full-time workers (those working 30 hours or more per week) applies to businesses with 50 or more employees. This mandates that large companies either provide affordable insurance or face penalties. The law has driven many employers to offer plans that comply with new coverage standards, making more consistent options available to employees.
Insurance policies can no longer exclude individuals with pre-existing conditions, which has expanded access for those who previously struggled to obtain affordable coverage. Additionally, the introduction of age-rating caps ensures that premiums cannot differ significantly based on age, particularly helping older individuals secure more reasonably priced plans.
| Key Impact Areas | Details |
|---|---|
| Marketplaces | Online platforms for comparing and purchasing plans, with subsidies for eligible individuals. |
| Medicaid Expansion | Increased eligibility in participating states, providing coverage for low-income adults. |
| Pre-existing Conditions | Insurers cannot deny coverage based on pre-existing conditions. |
| Essential Health Benefits | Insurers must provide coverage for a defined set of health services. |
| Employer Mandate | Large employers must provide coverage for full-time employees or face penalties. |
Consumers now have a range of affordable coverage options, with guaranteed protection for essential services, and protections against high out-of-pocket costs. These reforms are reshaping the health insurance environment by making coverage more accessible and standardized.
Eligibility Criteria for ACA Subsidies and Medicaid Expansion
Individuals and families may qualify for premium tax credits and Medicaid through specific income and residency requirements. For tax credits, household income must fall between 100% and 400% of the federal poverty level (FPL). Applicants must also be U.S. citizens or legal residents, and not eligible for other qualifying employer-sponsored plans.
Medicaid expansion is available to adults with incomes at or below 138% of the FPL, residing in states that have expanded the program. Eligibility extends to single adults, including those without children, who meet income and residency guidelines. In states that have not expanded Medicaid, eligibility remains more restrictive, often limited to specific low-income groups such as pregnant women, children, or people with disabilities.
It’s important to assess annual income against FPL guidelines to determine eligibility. Households that exceed 400% of the FPL may not qualify for subsidies but can purchase insurance through the marketplace without financial aid. Keep in mind that state-specific rules and income calculations can vary slightly, and periodic updates to the FPL should be considered when evaluating eligibility.
What You Need to Know About the Individual Mandate and Penalties
The individual mandate requires most U.S. citizens and legal residents to have health insurance or face penalties. For years, this mandate applied a tax penalty if an individual went without coverage for more than three consecutive months. However, starting in 2019, the penalty was eliminated at the federal level. People who don’t have coverage are no longer subject to a federal fine.
Some states, including California, Massachusetts, New Jersey, Rhode Island, and Vermont, have implemented their own mandates with penalties for non-compliance. These states impose fines based on income, household size, and the duration of time without coverage. The penalty can be a fixed amount or a percentage of household income, whichever is greater.
It’s crucial to assess your state’s requirements annually, as some penalties may still apply depending on local laws. If you fail to meet the insurance mandate, it’s important to understand how your state calculates penalties to avoid unexpected fines. Always check with your state marketplace or tax professional to ensure compliance.
How ACA Affects Employers and Employer-Sponsored Plans
Employers with 50 or more full-time employees must offer health coverage that meets minimum standards or face penalties. These standards include affordability and coverage of a minimum number of services. If an employer fails to provide this, they may be required to pay a fee for each employee who obtains subsidized coverage through the health insurance marketplace.
Employers must also inform employees about available health insurance options. This includes notifying them about government-run programs, such as Medicaid, if they meet eligibility criteria. The employer’s coverage must be deemed affordable–meaning employees’ premium costs do not exceed a specified percentage of their income. If the cost is too high, employees can opt for subsidized coverage through the marketplace.
For those offering insurance, there are several requirements related to plan design. These include covering essential health benefits and providing preventive services at no cost. Employers must ensure their plans are compliant with these provisions, which may require adjustments to existing policies.
Employers must also track employees’ work hours to determine whether they are full-time (defined as working 30 hours or more per week). This data is crucial for calculating penalties or avoiding compliance issues. Additionally, companies are obligated to report on their employees’ health coverage annually to the IRS and to employees themselves.
Smaller businesses (fewer than 50 employees) are not mandated to provide coverage, but they may still choose to do so. Some smaller companies may qualify for tax credits if they offer coverage through specific small business programs.
Common Mistakes to Avoid on Your ACA Basics Exam
One of the most common mistakes is misunderstanding the eligibility criteria for different programs. Be sure to distinguish between full-time and part-time employees as well as understand the specific income thresholds for subsidies. It’s also crucial to recognize which organizations are required to provide coverage and which are exempt based on employee count.
Another frequent error is failing to properly identify the penalties associated with non-compliance. These fines vary based on whether an employer offers coverage and whether that coverage meets affordability standards. Ensure you know the specifics of these penalties and how they apply in different situations.
Confusing the requirements for small businesses with those for larger companies is also a common mistake. Small businesses have different obligations, and knowing the size threshold (50 full-time employees) can help you avoid this error. Additionally, be aware of tax credits available for small businesses offering coverage through the right channels.
Finally, it’s important to review the reporting requirements. Employers must track their employees’ hours worked and report their coverage status to the IRS. Failing to understand these reporting obligations could lead to missing out on key details or misreporting, which could affect your results.
For more details on the specifics of compliance, consult reliable resources like the official U.S. Department of Health and Human Services website: www.hhs.gov.